Moving Payment at Delivery: Cash, Card, Certified Check and Balance Rules
The truck is outside your new home. The elevator is reserved. You are ready for the movers to bring everything inside.
Then the driver asks for a cashier’s check.
You were planning to use a credit card.
Or perhaps the payment method is correct, but the balance does not include the money you already paid at pickup. Maybe the invoice is higher than the estimate, and nobody has explained which charges must be paid now and which can be billed later.
These are problems worth resolving before delivery day.
Moving Payment at Delivery involves three separate questions: how you can pay, how much is properly due, and what the mover must release after receiving that payment.
For interstate household-goods moves, the carrier must identify the accepted payment method when preparing the estimate and repeat it on the Bill of Lading. The mover and its agents must honor that method at delivery unless you agree to a change in writing. That requirement appears in 49 CFR § 375.217.
This guide focuses on U.S. interstate household-goods moves for individual customers, especially shipments paid on a collect-on-delivery basis. Local moves, international moves, and employer-paid arrangements may involve different rules or contracts.
Moving Payment at Delivery: Understand These Three Amounts
Before choosing a payment method, separate the numbers on your paperwork.
The estimated total is the amount shown on the applicable written estimate.
The final shipment charges are the charges ultimately owed under the estimate, tariff, services performed, and applicable rules.
The delivery balance is the additional amount properly collectible at delivery after accounting for payments and credits already applied.
These amounts are not always identical. Federal rules limit what a carrier may collect at delivery under binding and non-binding estimates, even when other lawful charges remain payable later. See 49 CFR § 375.703.
Ask the mover to show all three amounts rather than sending one unexplained message:
Balance due: $4,800.
You should be able to see how that balance was calculated.
Can Movers Require Payment Before Unloading?
Yes. On a collect-on-delivery move, the carrier may require payment of the amount properly due before releasing the shipment. A request for payment before unloading is not, by itself, evidence of a scam.
FMCSA explains that a mover may refuse delivery and place goods into storage at the customer’s expense when the customer does not pay the transportation charges properly due. However, the carrier must also follow the federal limits on delivery collections. See FMCSA’s guidance on collecting moving charges.
The distinction is important:
A legitimate delivery payment is not the same as an arbitrary demand for more money.
Before delivery, ask when payment will be requested, how authorization works, and what receipt you will receive. Do not assume the company will unload everything first and collect payment afterward.
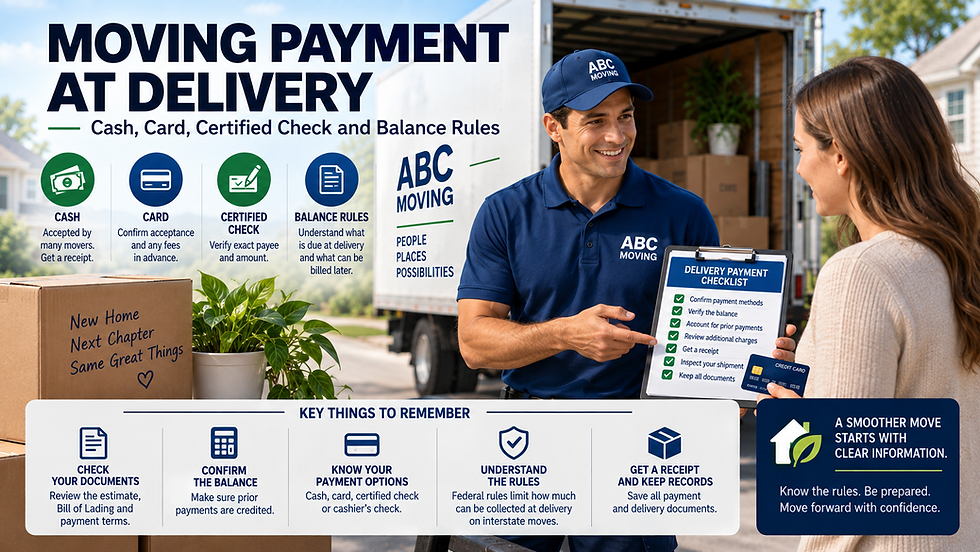
Cash, Card, Certified Check or Cashier’s Check?
There is no single payment method that every interstate mover must accept.
The right starting point is the payment provision in your estimate and Bill of Lading—not a card logo on the mover’s website. Federal estimate rules recognize several possible payment arrangements without requiring every carrier to offer all of them. See 49 CFR § 375.401.
Payment method | What to confirm before delivery | Record to keep |
Cash | Exact amount, authorized recipient, and receipt procedure | Dated receipt identifying the shipment |
Credit card | Acceptance for the delivery balance, card type, authorization process, and any disclosed fee | Transaction receipt and updated invoice |
Debit card | Separate confirmation of acceptance and your bank’s transaction limits | Transaction receipt and account record |
Certified check | Whether this specific check type is accepted, exact payee, and amount | Bank record and carrier receipt |
Cashier’s check | Exact payee, amount, and how any difference will be handled | Purchase record and carrier receipt |
Money order | Acceptance, issuer requirements, and whether multiple instruments are permitted | Purchase receipts and carrier acknowledgment |
Do not substitute one method for another without confirmation.
“Certified funds” can be used loosely in conversation. Ask the carrier to name the specific payment instruments it accepts.
Paying Movers in Cash
Cash can be an accepted payment method. The problem is not cash itself; it is an unexpected change, an unexplained amount, or payment without a reliable record.
Before handing over cash, confirm the shipment number, amount due, and person authorized to collect it. Request a receipt showing the carrier’s name, date, amount, and remaining balance.
Count the payment with the recipient and keep a copy of the signed acknowledgment.
Do not rely on:
The driver knows you paid.
Also keep any voluntary tip separate from the transportation payment. That makes it easier to identify exactly how much was credited toward the invoice.
If the written agreement accepts a card or bank check, a last-minute cash-only demand needs clarification—not an automatic trip to the ATM. The agreed-method requirement applies to the mover’s agents as well as the carrier. See 49 CFR § 375.217.
Paying by Credit or Debit Card
Ask specifically whether cards are accepted for the delivery balance. Acceptance for a booking payment does not establish the terms for every later payment.
Confirm whether payment goes through the office, a mobile terminal, or an online portal. Ask whether the cardholder must be present, whether a third party can pay remotely, and whether splitting the balance between approved methods is permitted.
For credit-card payments, federal rules address the carrier’s ability to obtain authorization at delivery. They also treat an accepted card payment as equivalent to payment by the other specified methods. See 49 CFR § 375.217 and 49 CFR § 375.221.
Check your available credit or debit transaction limit before moving day. Arrange any needed bank authorization early rather than discovering a restriction while the crew waits.
What about processing fees?
Ask for any proposed card fee in advance, including its calculation and where it appears in the payment terms.
Do not assume the same surcharge is permitted for every card. For example, Visa’s U.S. surcharge requirements prohibit surcharging Visa debit and prepaid transactions and set disclosure requirements for permitted credit-card surcharges.
A fee should not appear for the first time on the payment screen without explanation.
Certified Check vs Cashier’s Check
These are different banking instruments.
A certified check is drawn on the customer’s account. The bank verifies the check and reserves the funds.
A cashier’s check is issued by the bank and drawn on the bank’s own funds after the customer provides the money.
Citi’s explanation of certified and cashier’s checks describes this distinction.
Before obtaining either one, ask for the exact legal payee and written balance. Confirm that your bank offers the required instrument and that you can obtain it before the delivery appointment.
What if the balance changes after the check is issued?
Agree on the procedure before buying the check.
Ask how an additional legitimate charge would be paid and how an overpayment would be credited or refunded. Do not assume the driver can make change or accept another payment method.
Keep the bank’s purchase or certification record. Once you hand the check to the authorized recipient, obtain a separate receipt from the carrier.
Avoid buying an unnecessarily large check “just in case.” The Office of the Comptroller of the Currency’s cashier’s-check guidance explains that stopping or replacing a cashier’s check is not the same as canceling an ordinary personal check.
Can You Use a Personal Check, Bank Transfer or Payment App?
Do not assume so.
FMCSA advises customers to confirm accepted payment methods rather than assuming that personal checks or a familiar card will be accepted. The written terms control the arrangement. See FMCSA’s collection-of-charges guidance.
For a bank transfer or payment app, ask the carrier to confirm the recipient account, reference number, timing, and proof required.
Before using newly supplied payment instructions, verify them through a contact number already associated with your moving documents. Do not rely solely on an unexpected text containing a new account or payment link.
If a transaction appears pending, check its status before paying again. Request written confirmation of whether the first transaction failed, was canceled, or remains active.
Calculate the Balance After Deposits and Pickup Payments
Start with a payment reconciliation, not memory.
For a straightforward binding move with no additional charges:
Binding charges − payments credited to those charges = remaining balance
For example:
$6,000 − $2,000 already credited = $4,000 remaining
Ask the invoice to identify each prior payment, its date, who received it, and how it was applied. Federal rules require an honest, truthful invoice and tariff-consistent charges. See 49 CFR § 375.215.
Check broker payments separately
A broker arranges transportation; the carrier performs it. FMCSA explains their different roles in its Movers vs. Brokers guide.
If you paid a broker, ask both companies whether that payment is credited toward the carrier’s transportation charges, represents a separate brokerage charge, or includes both.
Do not assume every broker payment automatically reduces the carrier balance dollar for dollar. Equally, do not accept a carrier invoice that ignores a credit clearly promised in the documents.
Resolve the allocation before delivery.
How Much Can Movers Collect Under a Binding Estimate?
For the shipment and services included in a valid binding estimate, the binding amount is the starting point—not the binding amount plus an automatic 10%.
Certain customer-requested additional services and qualifying impracticable operations may be collectible separately. Federal rules also specify how changes involving additional goods or services must be handled.
Review 49 CFR § 375.403.
When reviewing the balance, use the applicable signed estimate. Do not use an early shopping quote if it was properly replaced before loading.
At the same time, a larger delivery invoice is not, by itself, proof that you agreed to a new binding price.
How the 110% Rule Affects a Non-Binding Delivery Balance
For a qualifying collect-on-delivery shipment under a non-binding estimate, the carrier generally cannot require more than 110% of that estimate for the estimated services before releasing the shipment. Certain permitted additional charges are treated separately.
The rule limits collection at delivery. It does not automatically cap the final lawful bill.
Under 49 CFR § 375.407, the mover must release the shipment when the required delivery amount, including applicable permitted additions, is paid.
Example with payments already credited
Assume a complete delivery, no separately collectible additional services, and $2,000 already credited toward the same carrier charges.
Calculation | Amount |
Applicable non-binding estimate | $6,000 |
110% of that estimate | $6,600 |
Final charges for the estimated services | $7,000 |
Prior payments credited | $2,000 |
Additional amount collectible at delivery for those services | $4,600 |
Potential remaining balance to be billed later | $400 |
The delivery calculation is:
$6,600 − $2,000 = $4,600
It is not $6,600 on top of the $2,000 already credited.
The 110% rule is often misunderstood as a limit on the entire final moving bill, but its main purpose is to limit how much a carrier can require before releasing a qualifying non-binding shipment at delivery. Additional lawful charges may still be billed later depending on the services performed and the applicable federal rules. For a detailed explanation of the calculation, exceptions, and delivery-payment limits, read: 👉 The 110% Rule in Interstate Moving: What Movers Can Legally Collect at Delivery
The extra 10% is not an automatic surcharge
If the actual lawful charges for those services are only $5,700, a $6,000 estimate does not authorize the mover to inflate the bill to $6,600.
With $2,000 already credited, the remaining amount would be $3,700, assuming no other charges.
FMCSA explains that when the bill is at or below 110% of the non-binding estimate, the actual bill may be collected in full. See FMCSA’s explanation of delivery payment arrangements.
Which Extra Charges May Be Payable at Delivery?
Two categories need particular attention.
Additional services you request
Services requested after the Bill of Lading is issued may be collectible at delivery under the applicable rules.
Ask the mover to identify the service, when you requested it, its price, and the supporting documentation. A fee labeled “extra service” is not enough.
Impracticable operations
These are operations defined in the carrier’s tariff, potentially involving specialized equipment or additional labor needed to complete pickup or delivery.
The amount collectible at delivery for this category cannot exceed 15% of all other charges due at delivery. That is a collection limit, not permission to add a flat 15% charge to every move. See 49 CFR § 375.703.
Also distinguish something you requested from a service the mover later determines is necessary. The notification, documentation, and billing rules can differ. These distinctions appear in § 375.403 and § 375.405.
Signing an acknowledgment does not automatically make every newly discovered charge collectible immediately.
What Happens to a Balance That Must Be Billed Later?
A deferred balance is not necessarily forgiven.
FMCSA explains that when covered charges exceed the non-binding delivery-payment limit, billing for the remaining charges must generally be deferred for at least 30 days, subject to the additional-service exceptions. See FMCSA’s estimating-charges guidance.
That is different from saying every customer automatically has 30 days to pay the entire move.
Later invoices have their own payment and credit rules. 49 CFR § 375.807 addresses credit periods and related charges.
When a later invoice arrives, request the calculation, tariff basis, prior-payment credits, and due date. Challenge an error promptly in writing rather than ignoring the bill.
Request the Weight and Charges Before Delivery
You do not need to leave every payment question until the truck arrives.
For a collect-on-delivery shipment, you can specifically request notice of actual weight or volume and charges and provide an address or telephone number for that notification.
Under 49 CFR § 375.521, the notice ordinarily must arrive at least one full 24-hour day before delivery, excluding Saturdays, Sundays, and federal holidays. The rule includes exceptions, including destination back-weighing and specified customer agreements or waivers.
Send the request early and also ask for the balance after credits, accepted payment methods, exact payee, and any separately collectible charges.
Check weight-based increases before unloading
When charges depend on weight, the freight bill must include copies of the supporting weight tickets. For an origin-weighed shipment, a reweigh request must be made after the billing weight and charges are disclosed but before unloading begins.
See 49 CFR § 375.519 and § 375.517.
What If Only Part of the Shipment Arrives?
Do not automatically pay as though everything was delivered.
Federal rules require applicable estimate-based delivery collections to be prorated by the weight delivered. They also address collections when one shipment travels on multiple vehicles.
Ask which inventory items arrived, where the rest are, how the delivered portion was calculated, and how earlier payments were credited. See 49 CFR § 375.407(c) and § 375.705.
Do not sign a receipt confirming complete delivery when the shipment is incomplete.
What If the Payment Fails or the Method Suddenly Changes?
First, separate a processing problem from a disagreement over the amount.
A declined card does not establish that the invoice is wrong. An approved invoice does not establish that a transaction succeeded.
Contact the carrier’s office and your bank as needed. Confirm whether the transaction was declined, authorized, pending, or completed before attempting another payment.
If the driver rejects the written payment method, ask the office to review the estimate and Bill of Lading. Keep any proposed change in writing and confirm that a replacement payment will not duplicate the first.
Do not assume that an ATM withdrawal, bank-check replacement, or transfer can be completed instantly. Arrange an agreed backup before delivery whenever possible.
What If the Mover Refuses to Release the Shipment?
Check the demand against the applicable estimate, allowable additions, prior payments, and agreed payment method.
Ask for an itemized invoice and a written explanation of the refusal. Preserve evidence of payments or payment offers, messages, employee names, shipment identification, and delivery details.
An improper refusal after an offer of the required amount can violate the shipment-release rules. Not every balance dispute is automatically a hostage situation, but an unexplained demand deserves prompt attention. See 49 CFR § 375.407.
You can use FMCSA’s moving-fraud complaint resources to report suspected violations. Complaints support enforcement; they do not guarantee an immediate delivery or decide your individual claim. For a serious dispute, consider legal advice. If there are threats or an immediate safety concern, contact local authorities.
Paying the Bill Is Different From Accepting Everything in Good Condition
A payment receipt records money received. A delivery inventory records what arrived and its condition.
Do not treat them as interchangeable.
After unloading, verify the inventory and note visible damage or shortages. Do not confirm that all goods arrived in good condition merely because payment has already been processed.
Federal rules prohibit language on the delivery receipt or shipping document that purports to release the mover or its agents from liability. See 49 CFR § 375.701.
Do not invent your own damage deduction
Do not simply subtract your estimated repair cost from the delivery balance. Request any agreed credit in writing and follow the claims process.
Shortage, partial-loss, and destruction situations have separate payment rules, so obtain the correct calculation rather than applying an arbitrary deduction. See 49 CFR § 375.707.
A notation on the receipt is useful evidence, but it is not, by itself, a complete written claim under 49 CFR § 370.3.
Can You Dispute a Credit-Card Charge After Delivery?
Contact your issuer promptly about a genuine unauthorized charge, duplicate transaction, or billing error.
The CFPB advises sending a written billing-error notice no later than 60 days after the issuer sends the statement showing the error. Problems involving defective services may involve a different dispute process. See CFPB guidance on fixing credit-card billing mistakes and disputing a charge.
A temporary card credit does not necessarily resolve the carrier’s invoice or a separate cargo claim. Federal moving rules specifically address reversed card payments in 49 CFR § 375.221.
Keep the invoice, transaction record, estimate, and correspondence. Describe the actual problem accurately rather than treating a chargeback as a substitute for investigating the bill.
A Payment-Confirmation Message to Send Before Delivery
Send a message like this to the carrier’s office while there is still time to resolve discrepancies:
Please confirm the payment arrangements for shipment [number] before delivery. Please show the applicable estimate amount, total charges, payments already credited, additional amount due at delivery, and any balance that will be billed later. Please also confirm the accepted payment methods, exact payee, any processing fee, and how payment will be authorized and receipted. For any amount above the estimate, please identify the service, tariff basis, supporting documentation, and whether the charge is collectible at delivery. I will be reachable at [telephone number] and [email address].
Save the reply with your moving documents. Share the confirmed arrangements with anyone receiving the shipment on your behalf.
FAQ About Moving Payment at Delivery
Do interstate movers have to accept credit cards?
No universal card-acceptance requirement applies. The mover must state and honor the agreed payment method, subject to a written change you accept. Check 49 CFR § 375.217.
Is a cashier’s check the same as a certified check?
No. A cashier’s check is issued against the bank’s funds; a certified check is drawn on the customer’s account with bank certification. Confirm which one the carrier accepts before obtaining it. See Citi’s comparison.
Does the 110% rule mean I owe an extra 10%?
No. It is a collection limit for qualifying non-binding moves, not a mandatory surcharge. The actual lawful charges may be lower, and certain additional services may be treated separately. See FMCSA’s payment-arrangement guidance.
Should payments made at pickup reduce the delivery balance?
Payments credited toward the same charges should be accounted for. Request a reconciliation rather than assuming every earlier payment—including a possible separate broker charge—has the same treatment.
Does paying at delivery remove my right to file a damage claim?
Payment and claim documentation are separate issues. Delivery receipts must not contain language releasing the mover from liability. Preserve evidence and follow the claims procedure. See 49 CFR § 375.701.
Can I wait 30 days to pay the entire move?
Not simply because you have heard of the 110% rule. A qualifying deferred balance is different from the amount properly due to obtain delivery. Separate credit arrangements must be understood and documented.
Final Moving Payment at Delivery Checklist
Confirm the applicable estimate and whether it is binding or non-binding.
Obtain an invoice showing prior payments, credits, and the remaining balance.
Separate amounts collectible at delivery from amounts to be billed later.
Confirm the accepted method, exact payee, and authorization procedure.
Arrange bank funds, card limits, and any agreed backup method in advance.
Review supporting records for additional or weight-based charges.
Keep payment receipts separate from delivery-condition acknowledgments.
Retain copies of the estimate, Bill of Lading, inventory, invoice, and correspondence.
Moving Payment at Delivery should not require a hurried decision beside the truck.
Know the accepted method. Know how the balance was calculated. Know which charges are payable now. Then obtain a receipt and inspect the delivered shipment without confusing payment with a waiver of your rights.
The most useful payment conversation happens before the driver arrives—when there is still time to correct an invoice, obtain the right check, or resolve an authorization problem.
Related Interstate Moving Guides
Moving Tariff Explained: Why It Controls Your Final Moving Charges
Binding vs Non-Binding Moving Estimates: What Interstate Movers Don’t Explain
Bill of Lading for Interstate Moving: What Customers Must Check Before Signing
Interstate Moving Reweigh Rights: Can You Request a Reweigh?
Can Movers Hold Your Belongings Hostage? What Interstate Customers Should Know
This guide provides general consumer information, not legal advice for an individual dispute.
Author:
Written by: Arthur Brooks — Owner & Operations Manager
Interstate moving, storage & claims operations expert
Just Movers / BY Logistic LLC
Dallas, TX • Miami, FL